

登入並加入群聊,暢想更多精彩內容
美國第三季度財報季拉開帷幕,但銀行業績未能推動大盤繼續上漲。周二,道指下跌0.35%,標普500微跌0.02%至7805.45點,納指下跌0.15%至27204.38點。標普仍接近歷史高位,顯示投資者尚未明顯撤離股票市場,但在高估值與高融資成本并存的環境下,企業盈利能否持續增長,將成為市場進一步上行的重要條件。
 US Banks Earnings Overview, Source: SEC
大型銀行的業績反映出美國經濟仍具韌性,同時也暴露出高利率帶來的壓力。摩根大通第三季度市場業務收入同比增長15%,其中股票交易收入增長49%;然而,部分銀行指出,9月債市波動已經拖慢投行業務。
交易收入增長能夠改善當季盈利,卻未必代表企業融資與投資活動同步增強。科技板塊則面臨新的競爭壓力,市場對中國存儲芯片技術進展的關注升溫,令部分芯片股承壓。接下來的財報需要回答:盈利增長是否足以支撐當前估值,尤其是AI相關投入能否轉化為穩定回報?
美債收益率回落提供了一定緩沖,但整體融資環境依然偏緊。美國10年期國債收益率下降約3個基點至5.216%,30年期降至5.562%,兩年期則略升至4.791%。長端回落、短端保持堅挺,尚不足以說明加息預期出現明顯松動。
US 10 Year Treasury Yield, Source: Tullett Prebon
今晚墨爾本時間23時30分公布的美國9月CPI,將成為下一輪定價的重要依據。市場預計整體CPI同比由3.4%升至3.6%,核心CPI環比增長約0.2%。投資者不僅要觀察能源對整體通脹的影響,更需判斷價格壓力是否向其他領域擴散。若核心通脹高于預期,長端收益率的回落可能受到限制,股票估值也將面臨進一步檢驗。
DXY H1
美元指數隔夜回落約0.4%至102.19,但單日調整尚不足以改變利差與避險需求對美元的支撐。澳聯儲最新會議紀要繼續提示通脹持續偏高的風險,為澳元提供一定政策支持;不過,AUDUSD仍同時受到美元走勢及全球風險偏好的影響。
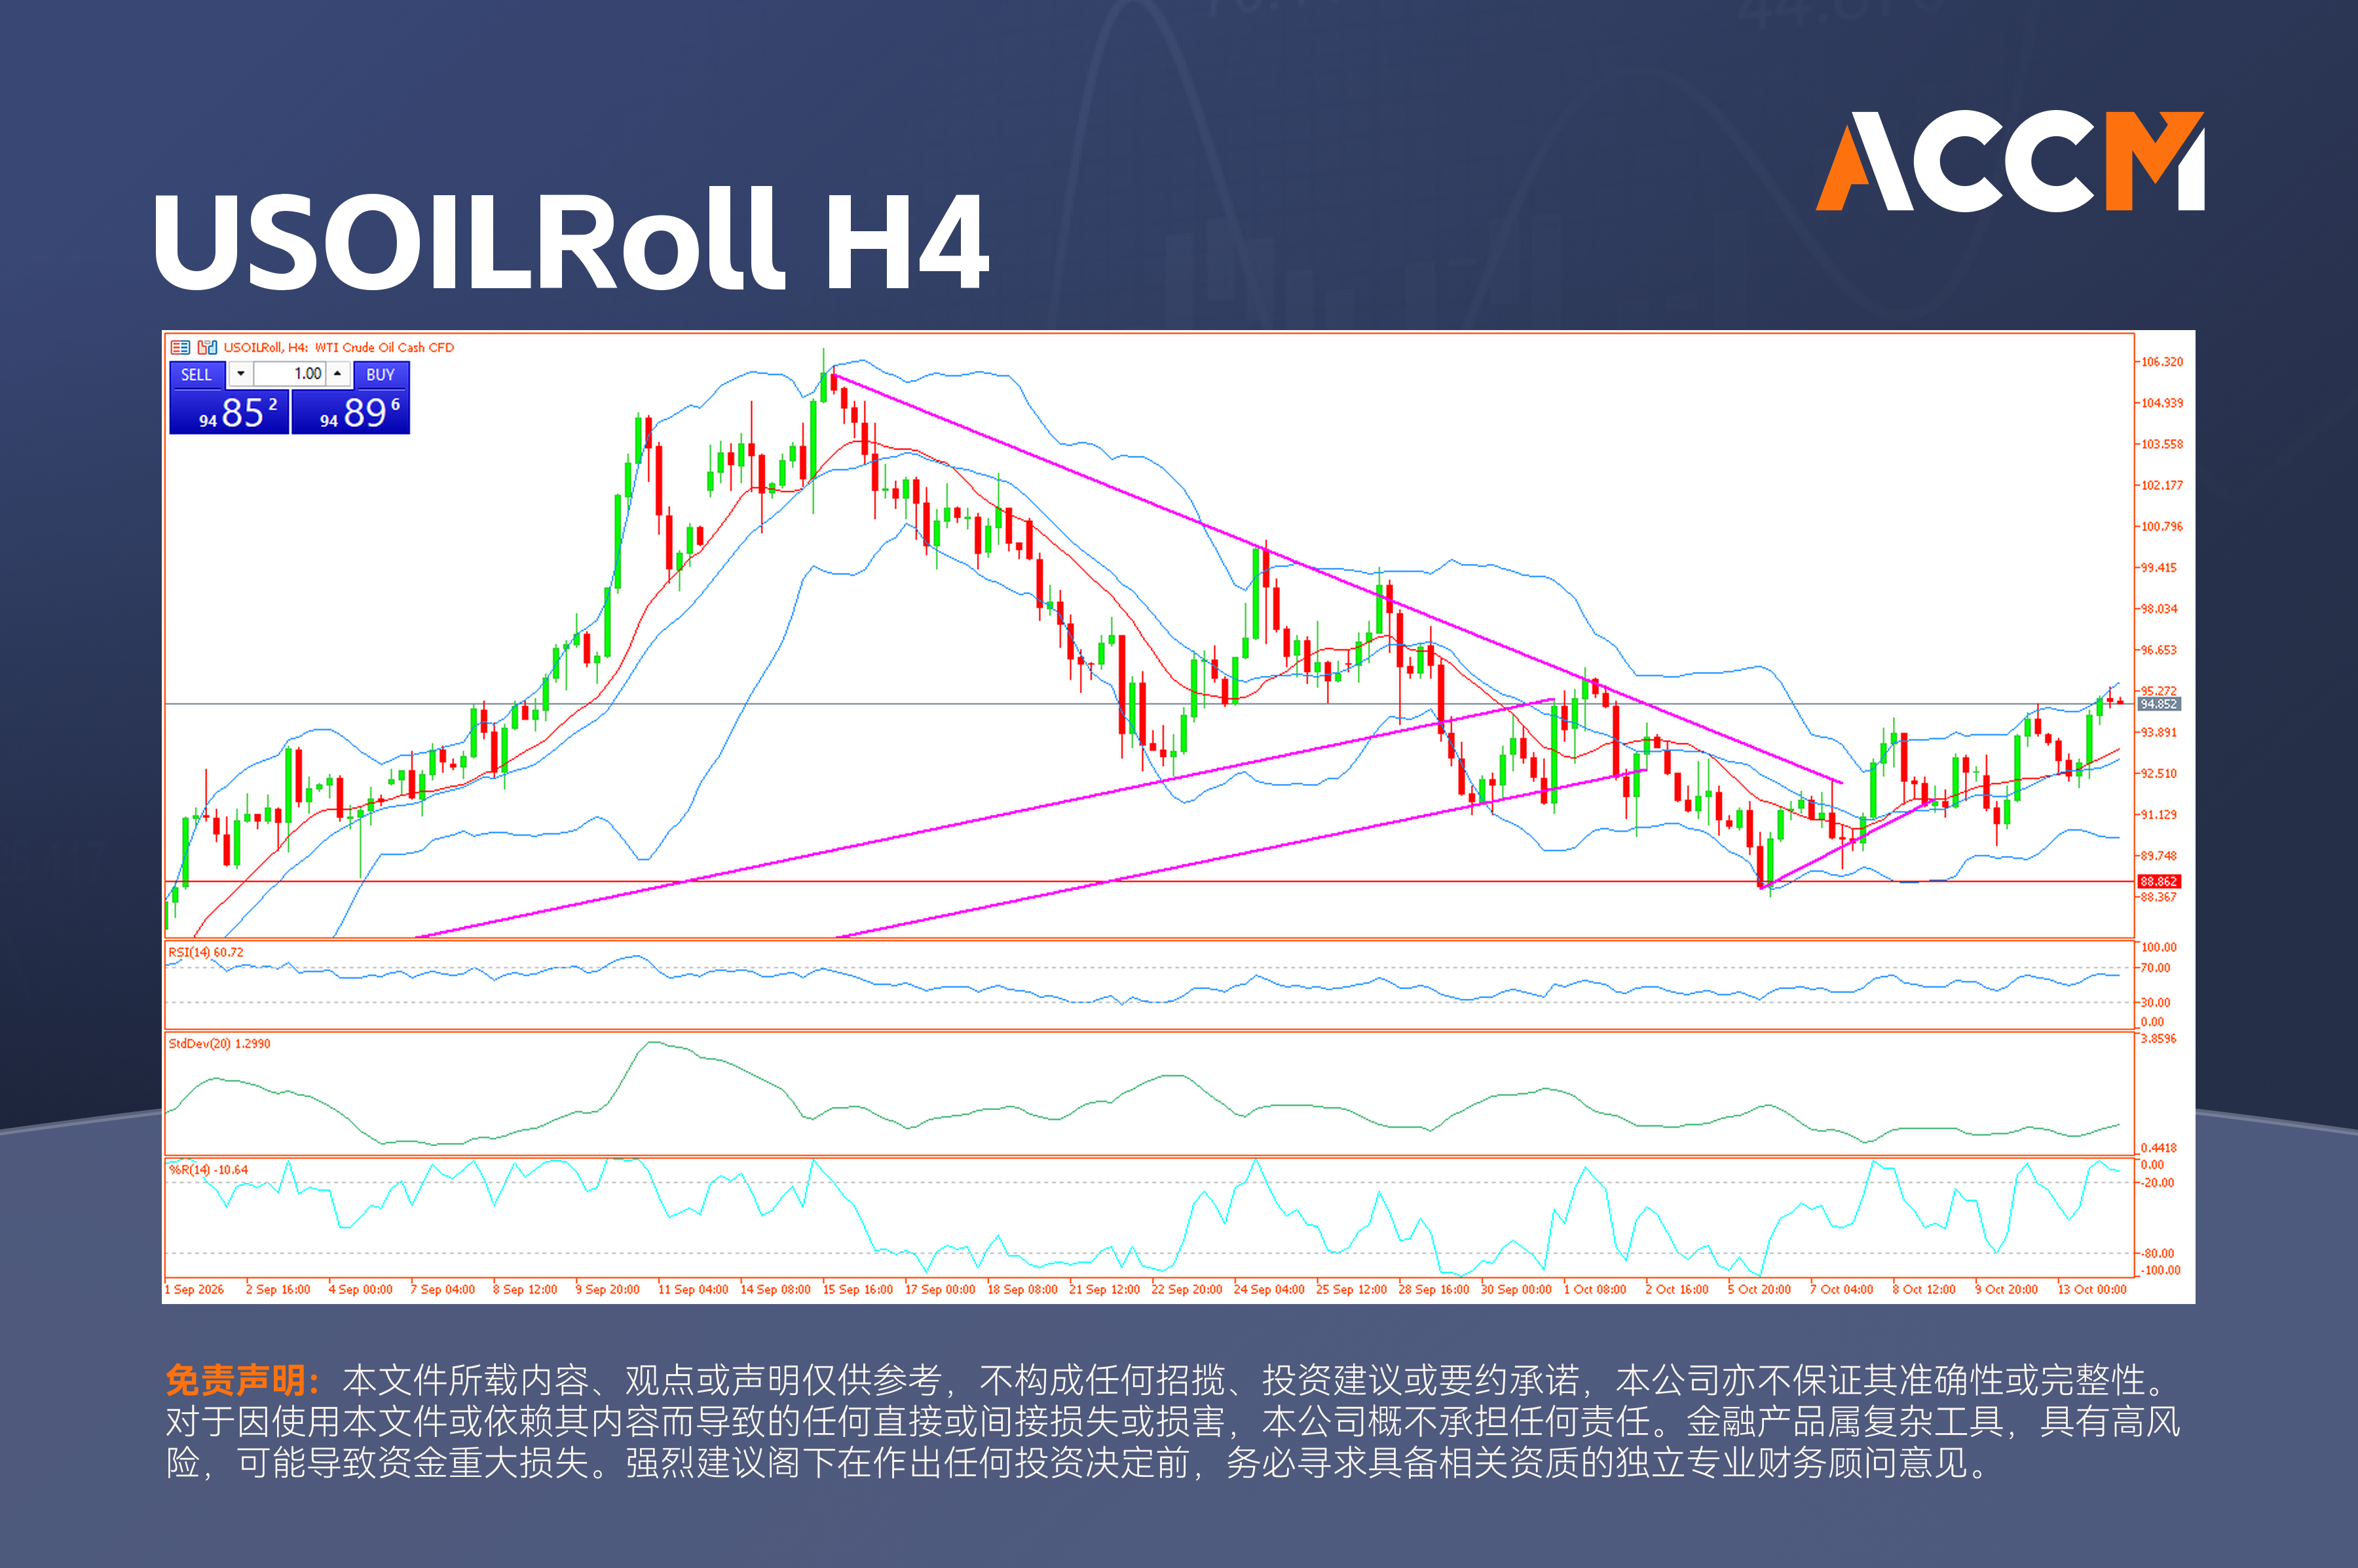
USOILRoll H4
原油方面,布倫特下跌0.9%至每桶105.69美元,WTI則上漲0.4%至94.14美元。市場一邊評估俄羅斯柴油供應增加的可能性,一邊關注中東能源設施與運輸路線的安全風險,供應改善預期尚未消除地緣溢價。
若油價持續處于高位,企業成本與居民購買力仍將承壓。今晚的通脹數據,能否讓市場相信美國經濟可以在維持增長的同時控制價格壓力,將決定近期股匯債市場的下一步方向。
風險提示:
The information contained in this market commentary is of general nature only and does not take into account your objectives, financial situation or needs. You are strongly recommended to seek independent financial advice before making any investment decisions.
Trading margin forex and CFDs carries a high level of risk and may not be suitable for all investors. Investors could experience losses in excess of total deposits. You do not have ownership of the underlying assets. ACCM (V) Ltd is the product issuer and distributor. Please read and consider our Product Disclosure Statement and Terms and Conditions, and fully understand the risks involved before deciding to acquire any of the financial products provided by us.
The content of this market commentary is owned by ACCM (V) Ltd. Any illegal reproduction of this content will result in immediate legal action.
Copyright © 2026 FX110.COM.TW All Rights Reserved

